For wholesale & sophisticated investors
Put your capital to work in secured Australian business loans with your name on the mortgage.
Co-fund short term business loans with HomeSec Business Finance, one of Australia's longest standing and most experienced private business lenders. You choose each loan, you're registered on the title, and our own money sits alongside yours.
- Lending since 2004
- Our money in every loan
- Founding member of ASTLA
- Returns
- 12–18% p.a.
- Lending since
- 2004
- Maximum LVR
- 80% residential
- Loan terms
- 1–12 months
- Per loan
- $100k to several million
A simpler, more transparent way to earn strong returns from Australian property.
Investor Opportunities lets wholesale investors lend directly into individual business loans arranged and co-funded by HomeSec Business Finance, an Australian private lender founded in 2004. Each loan is secured by a registered first or second mortgage over Australian real estate, runs for 1 to 12 months, and pays returns of 12% to 18% p.a. You are named on the mortgage for your share.
It isn't a fund. There's no pooled money, no unit price, no redemption queue — just a real loan, a real property, and your name on the security. We fund most of our loans off our own balance sheet; on some, we invite a small group of investors to come in alongside us.
Why investors choose direct
Great returns, with the safety net of being in control.
Hundreds of managed funds pay single-digit returns while asking you to hand over control. Co-funding flips that around.
Your name on the mortgage
You're registered on the title for your exact contribution — not a unit holder in someone else's pool.
You choose every loan
Each opportunity comes with a full due diligence pack. You decide yes or no, and how much. No obligation, ever.
Our money in every deal
HomeSec co-invests its own capital in every loan it offers — often 50/50. We practise what we preach.
Paid straight to you
Principal and interest go directly to your own bank account — not to us, not into a fund.
No redemption freezes
Repaid at maturity. Want out early? We'll buy out your share and repay your principal.
No construction or development
Only straightforward business loans over existing property, with a maximum 80% LVR on residential.
Direct vs pooled
Lower returns and less control shouldn't come as a package deal.
In 2026 several Australian credit funds limited or froze withdrawals. Here's why a direct, registered position works differently.
| Typical pooled mortgage or credit fund | Co-funding with HomeSec | |
|---|---|---|
| What you own | Units in a fund | A share of a specific loan — named on the mortgage |
| Who chooses the loans | The manager | You, from a full due diligence pack |
| What you can see | Monthly, averaged reporting | The property, the borrower, the purpose and the exit |
| Getting your money out | Redemption requests — can be limited or frozen | Repaid at maturity, or bought out early by HomeSec |
| Manager's own money | Often none in the loans | In every loan, alongside yours |
| Construction & development | Often a large share of the book | None |
| Where repayments go | Into the fund | Straight to your bank account |
| Returns | Often single-digit | 12%–18% p.a. |
Read the full comparison: direct mortgage investment vs pooled funds →
“You are not left wondering how things work — and your return, or the security of your funds, isn't dependent on a whole heap of things going exactly right.”
Paul Stone, Joint CEO & FounderHow it works
Five steps. It really is that simple.
- 01
Register your interest
Tell us about yourself and confirm you're a wholesale or sophisticated investor. Our Funding Manager will call — or jump on a Zoom.
- 02
Review a loan pack
When a loan fits, we email its due diligence pack: the property, the borrower, the purpose, the exit, the LVR, the term and the rate.
- 03
Say yes — or pass
If you like it, tell us how much you'd like to contribute. If not, there's no obligation. You choose every loan.
- 04
Settle in your name
The loan agreement is prepared in your name, the borrower signs with their solicitor, and the mortgage is registered with you on it.
- 05
Get paid
Interest and principal are paid straight to your account. When the loan repays, take the next one — or don't.
Returns
Double-digit income, secured by bricks and mortar.
Borrowers pay a premium for speed, flexibility and short terms — not because they're weak. Most are established, thriving businesses unlocking equity in property. That premium is what you earn.
Backed by Australian property
One of the world's most resilient property markets — and a buffer on top.
In the modern era, national home values have never fallen more than about 10% in a downturn — and every fall has recovered. We lend to a maximum of 80% LVR on residential property — lower on commercial — so there's a 20%+ equity cushion before your capital is in play.
How the equity buffer protects your loan
Share of the property's value
- Your loan — no more than 80% of the property's value (lower on commercial)
- Deepest modern national fall — about 8–10% (2017–19)
- Equity still protecting you — about 10% of value left even after that fall
 Sydney
 Melbourne
 Brisbane
 Perth
 Adelaide
 Gold Coast
The strength and resilience of the Australian property market → Our lending rules →
Private credit in 2026
The year pooled funds hit the brakes.
Shield and First Guardian. Bathla. Redemption limits across well-known credit funds. What went wrong — and why a registered, loan-by-loan position is built differently.
What is a redemption freeze — and why did funds gate in 2026?
A redemption freeze stops investors withdrawing from a fund. How fund gating works, why Australian private credit funds froze in 2026 and how to avoid it.
Is private credit safe? A 10-point test for 2026
Is private credit safe? After the 2026 fund gates and ASIC's enforcement warning, use this 10-point test to score any private credit investment first.
The Bathla collapse: what it means for private credit investors
The Bathla collapse and private credit: which funds were exposed, why construction, land and unsold-stock loans carry more risk, and what investors can do now.
The private lending experts
Founded in 2004. Lending our own money the entire time.
HomeSec Business Finance is one of Australia's longest standing and most experienced private business lenders, and a founding member of the Australian Short Term Lenders Association. Both joint CEOs are involved in every loan we fund — including the ones you co-fund.
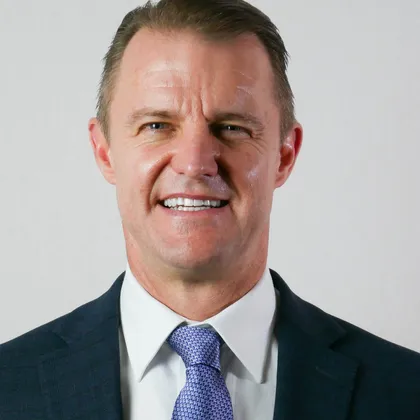
Paul Stone
Joint CEO & Founder
Founded HomeSec Business Finance in 2004 and wrote its first private business loan. Involved in every loan decision since.
Jason Brockmuller
Joint CEO
Runs credit policy and the second-mortgage book. With HomeSec since 2008 and involved in every loan decision.
Catriona Anderson
General Manager
Signs off every credit decision the team writes. With HomeSec since 2005.
Who co-funds with us
Built for people who've already made the money.
Now it's about enjoying life and healthy returns — with full control. Our investors can be anywhere in Australia or the world: review a pack on your phone, fund from your bank's app, and get on with your day.
Investor insights
All insights →- Private creditWhat happened to Shield and First Guardian — and what investors can learn
- Income investingAlternatives to term deposits in 2026, ranked by risk
- Pillar guidePrivate credit in Australia: the 2026 investor's guide
- Private creditContributory vs pooled mortgage funds (and direct co-funding) explained
- SMSF investorsCan an SMSF invest in private mortgages? How SMSFs lend, the rules and the tax
- High-net-worth investingWhere to invest $1 million in Australia: where secured lending fits
Questions
What investors ask us first.
Can't see your question? Call our Funding Manager on 03 9017 8277, 7 days — or browse the full FAQ.
What is Investor Opportunities?
Investor Opportunities is the investor program of HomeSec Business Finance, an Australian private lender founded in 2004. Wholesale investors co-fund individual short term business loans secured by registered first and second mortgages over Australian real estate. You choose each loan, you are named on the mortgage for your share, and HomeSec's own money sits in every loan alongside yours.
Is this a managed fund or a pooled mortgage fund?
No. You don't buy units in a pool. You lend into a specific loan you've reviewed, and you're registered on the mortgage for your exact contribution, alongside HomeSec. There is no pooled money, no unit price and no redemption queue.
What returns can I earn?
Returns are 12% to 18% p.a. on the loans you choose. The rate is set loan by loan and shown in each loan's pack before you commit. Borrowers pay a premium for speed, flexibility and short terms — that premium is what you earn.
How much can I put into each loan?
You decide, loan by loan. Co-funders typically put anywhere from $100,000 to several million dollars into each loan, and there is never any obligation to take a loan. HomeSec co-invests its own money alongside you.
Can I get my money out before the loan matures?
Yes. If you want out early, HomeSec will buy out your share and repay your principal. You can also stop co-funding at any time — once your current loans are repaid, you simply don't take the next one.
What security protects my investment?
A registered first or second mortgage over Australian residential or commercial real estate, with your name on it. The maximum LVR is 80% on residential property and lower on commercial, leaving an equity buffer if a property ever has to be sold.
Do you fund construction or development loans?
No. We only fund straightforward business loans secured against existing real estate. No construction, no development, and no unusual properties that would take a long time to sell.
Does HomeSec invest its own money?
Yes — in every loan. HomeSec funds the majority of its loans from its own balance sheet and co-invests in every loan it offers to investors, often 50/50. Its capital sits in the same loan, on the same mortgage, as yours.
How do I qualify as a sophisticated or wholesale investor?
Most people qualify with a qualified accountant's certificate, no more than two years old, showing net assets of at least $2.5 million or gross income of at least $250,000 in each of the last two financial years. Companies and trusts controlled by a qualifying person can qualify too.
Can my SMSF co-fund loans?
Yes. Many of our co-funders use their self-managed super fund as well as funds in their own name. The loan and mortgage are in the name of the SMSF's trustee and repayments go to the fund's bank account. Check your trust deed and investment strategy allow it.
Register your interest
Get your money working for you.
Tell us a little about yourself. Our Funding Manager will be in touch during business hours — we'd love to have a chat, and jump on a Zoom if that suits you.
- No obligation to take any loan
- Your name on every mortgage you fund
- HomeSec's own money in every deal